Dog Bite Insurance Claim Lawyers in Summerville
- Free consultation
- No fee unless we win
- Available 24/7
The dog that bit you may belong to someone you wave to every morning. It might be the retriever next door, your brother's rescue mix or a coworker's shepherd at a Saturday cookout. The medical bills still arrive, and you have no wish to sue a friend. Dog bite insurance claim lawyers in Summerville start from how these claims usually run. The claim goes to the owner's insurance company, and the policy pays when its coverage applies.
South Carolina's dog bite statute, Section 47-3-110, makes a dog's owner or keeper liable for a bite. It covers bites in a public place and bites on private property where the victim was lawfully present. Homeowner and renter policies often carry personal liability coverage built for claims like that. The South Carolina Department of Insurance calls it an all-purpose liability policy that goes with the policyholder beyond the property line. Auto and boating accidents are among its exceptions. Whether a given policy pays, and how much, turns on its exact terms and on facts your lawyer checks.
Jack C. Frost and Tara L. Frost, who are married, practice together as Frost Law Group. As a Dorchester County Magistrate Judge, a role that ended in August 2025, Tara saw from the bench how much preparation and credibility count. The firm handles bite claims against homeowner, renter and landlord policies, including claims where the owner is family. Tara and Jack know a bite claim can involve someone who will still share a fence line with you when it closes.
Call Frost Law Group at (843) 419-6653 for a free, confidential consultation about the bite and the coverage behind it. Have the owner's name ready, along with any insurer name the owner has already shared.
Free case review
Tell us what happened. An attorney will explain your options and what to do before you talk to the insurance company.
On this page
- How Dog Bite Insurance Claim Lawyers in Summerville Pursue a Policy, Not a Friend
- When a Relative's Dog Bites, What a Summerville Dog Bite Claim Attorney Explains
- Homeowner and Renter Policies a Summerville Dog Attack Insurance Lawyer Checks
- Landlord Coverage Questions a Summerville Dog Bite Injury Lawyer Sorts Out
- What an Adjuster Asks For and How a Summerville Dog Bite Attorney Responds
- Dog Bite Insurance Claim Lawyers in Summerville Who Keep the Claim Neighborly
How Dog Bite Insurance Claim Lawyers in Summerville Pursue a Policy, Not a Friend
Many people picture a bite claim as court papers handed to a neighbor at the front door. A claim can begin far more quietly, with a letter to the owner's insurance company. Frost Law Group can write that letter as soon as it knows which company issued the owner's homeowner or renter policy. From then on, most of the conversation can run between a lawyer and an adjuster.
In insurance terms, you become a third-party claimant. That means a person outside the insurance contract who asks the policy to pay for harm the policyholder must answer for. What any policy may pay depends on its limit, its terms and the medical proof. No careful lawyer names a figure before reviewing all three.
Does My Neighbor Pay a Deductible on My Bite Claim?
Picture a neighbor's beagle slipping under a shared fence on a street off Old Trolley Road. It bites you in your own side yard, and the neighbor worries about a deductible coming out of pocket. The Department of Insurance's homeowner FAQ says most homeowner forms apply deductibles to Section I losses on the property side of the policy. It adds that deductible provisions do not apply to Section II losses, which include personal liability and medical payments to others. A given policy's wording still controls, so that answer needs checking against the policy itself before anyone repeats it to the neighbor.
Will a Claim Cost My Neighbor Their Homeowner Policy?
South Carolina limits when an insurer may cancel a homeowner policy in the middle of its term. After a new policy's first 120 days, Section 38-75-730 allows mid-term cancellation only for listed reasons, such as unpaid premium or a material misrepresentation. A refusal to renew at the end of a term works differently. Section 38-75-740 requires written notice at least 60 days before the policy expires, stating the precise reason. The Department of Insurance's FAQ also warns that claims can lead an insurer to decline renewal even when the policyholder was not at fault.
Who Pays for the Neighbor's Lawyer if a Suit Is Filed?
A bite suit typically names the owner or keeper, since Section 47-3-110 places liability on them. In First Financial Insurance Co. v. Sea Island Sport Fishing Society, a 1997 decision, the liability policy gave the insurer the right and duty to defend suits against its insured. The South Carolina Supreme Court said that duty generally turns on the complaint's allegations. When a policy carries that duty and the complaint alleges a covered claim, the insurer generally provides the defense. Jurors generally do not hear about the coverage either. Rule 411 of the South Carolina Rules of Evidence bars proof of liability insurance on whether a person acted wrongfully. It still allows that proof for other purposes, such as showing ownership or control.
A Stranger's Loose Dog and the Owner's Homeowner Coverage
When a loose dog bites you on a sidewalk near Bacons Bridge Road, the first problem is a name. Section 47-5-100 has public health officials order the owner of a biting dog to quarantine it for at least ten days. That order has to reach a specific person. With the owner's name and address in hand, Frost Law Group can ask which company insures the household. The Department of Insurance describes homeowner liability coverage as reaching accidents away from the insured property, so a sidewalk bite may still fall within the owner's policy.
When a Relative's Dog Bites, What a Summerville Dog Bite Claim Attorney Explains
Can you make a claim against your own mother's homeowner policy? South Carolina's bite statute carves out no exception for family. Section 47-3-110 covers a bite on the owner's own property when the victim was there lawfully, and an invitation from the relative who owns or lives in the home supplies that. Frost Law Group handles these family claims with the relationship kept in view. It also handles injury claims for bitten children, such as a grandchild hurt at a grandparent's house, where court-approval rules can shape a settlement.
The harder question is whose policy applies and whether the injured relative counts as an insured under it. A homeowner policy typically defines who counts as an insured, and those definitions can settle coverage before fault ever comes up. Dog bite insurance claim lawyers in Summerville read those definitions before advising a family, because the answer depends on the wording and on where each person lives.
Siblings and Other Relatives Living in a Separate Home
Say your sister's dog bites you during Sunday dinner at her house in Knightsville. You live across town in your own place. In that setting you stand much like any other guest hurt on the property. The Department of Insurance describes homeowner medical expense coverage as paying for injuries on the premises to anyone who is not an insured. A separate household often keeps a visiting relative outside the policy's definition of an insured. Frost Law Group presents your side of the claim, while your sister notifies her insurer and answers its adjuster's questions.
Relatives Who Share the Dog Owner's Roof
The picture changes when the bitten relative lives with the dog's owner. A homeowner policy's definition of an insured may include relatives in the same household. The agency's own description of medical expense coverage leaves out anyone who is an insured. Liability coverage may treat a claim by one insured against another the same way. A lawyer reads the definitions and exclusions line by line before telling a family what the policy may do. When that policy does not respond, other sources may, such as the injured person's own health plan.
A Cousin Keeping the Dog for Its Owner
Section 47-3-110 reaches the owner and any person who keeps or cares for the dog. Suppose your cousin in Ladson is keeping her brother's dog while he works out of state. The dog bites you on her porch. Both the brother and the cousin may answer for the bite, which can put two policies in play. The owner's liability coverage may travel with him. The cousin's own liability and medical expense coverage may reach injuries on her premises. Which insurer pays first depends on both contracts, so a lawyer can notify both and watch which adjuster takes the lead.
Homeowner and Renter Policies a Summerville Dog Attack Insurance Lawyer Checks
The South Carolina Department of Insurance tells homeowners to read the policy itself to learn its limits. Frost Law Group can apply that same rule from the other side of the claim. The declarations page, the policy's summary of each coverage and its limit, is the natural place to start. According to the agency, home insurance packages for owners and renters usually include personal liability and medical payments coverage.
The agency's FAQ places those two coverages in Section II of a homeowner policy. Section I covers the dwelling, other structures, belongings and extra living costs after a covered loss. A bite claim draws on Section II. What any policy pays depends on its limits and wording, and dog bite insurance claim lawyers in Summerville read both sections before estimating anything.
Personal Liability Coverage for the Bite Itself
Personal liability coverage generally answers when the policyholder is legally responsible for bodily injury to someone else. Under Section 47-3-110, that responsibility turns mainly on ownership or keeping and on where the bite happened, not on carelessness. That proof sits at the center of every strict liability dog bite case Frost Law Group takes on. The limit on the declarations page generally caps what the insurer pays. The Department of Insurance adds that homeowners can buy additional liability coverage for a nominal premium, so any added coverage is worth asking about.
Medical Payments Coverage for Bite Treatment
Medical payments coverage works differently from the liability part of a policy. Frost Law Group can check for it first when a friendly neighbor wants the medical bills paid without a dispute over fault. By the agency's description, this coverage pays medical bills up to a fixed amount for each person, whether or not anyone is legally liable. That can cover an emergency visit whether or not the owner is ever found liable.
Bites on the Policyholder's Own Premises
The agency describes this coverage as paying for someone hurt on the insured property who is not an insured. A dinner guest bitten in a friend's kitchen fits that description. So does a letter carrier bitten on a porch step. The declarations page shows the per-person amount, which may fall well short of the cost of a serious bite.
Bites Away From Home Caused by the Owner's Pet
As the agency explains it, the same coverage can pay for injuries off the property when the policyholder, a family member or the family's pet caused them. A bite on a neighborhood walking path may therefore qualify under the owner's policy. Coverage for that bite turns on the wording in the owner's contract, so the full policy matters more than any summary of it.
Renter Policies When the Dog Owner Leases
Tenants keep dogs too. The Department of Insurance's buying guidance says tenants need insurance for their belongings. It also says everyone needs protection against liability for accidents that injure others. Not every tenant buys a policy. When a renting owner carries none, the claim runs against the owner personally, and collecting depends on that person's means. Whether renter coverage exists therefore shapes every later step.
Breed Terms and South Carolina's Dangerous Animal Statute
Section 47-3-710(C) says no animal is a dangerous animal solely because of its breed. That sentence defines a term in the state's dangerous animal article. It does not speak to what an insurance contract covers. A policy's own terms may address certain dogs, and only the policy language shows whether it does. Frost Law Group can read that language rather than accept an adjuster's summary of it. Separately, an owner of a dog that qualifies as dangerous must register it with proof of liability coverage or a surety bond, a written promise from a bonding company to pay, of at least $50,000.
Landlord Coverage Questions a Summerville Dog Bite Injury Lawyer Sorts Out
In Clea v. Odom, decided in 2011, the South Carolina Supreme Court restated a common-law rule, one that courts built through their own decisions. A tenant's guest generally cannot hold the landlord liable for injuries from an animal the tenant keeps on leased property. That rule usually keeps a landlord's liability policy out of a bite inside a tenant's unit or fenced yard. The tenant's own renter policy, if one exists, becomes the likely source of payment.
Summerville itself crosses county lines. Census Bureau estimates for 2025 place 44,724 of the town's people in Dorchester County, with 5,798 across the Berkeley line and 2,655 across the Charleston line. A rental in any of those parts follows the same state rules on landlord liability. Whether a landlord shares responsibility turns on control, knowledge and care of the dog, and dog bite insurance claim lawyers in Summerville test each against the record.
Common Areas the Complex Controls
Clea also marked the exception. The dog there lived chained to a tree in a shared area of a two-building complex. There was evidence the landlord knew it had attacked a child before. The Court held that a landlord who controls a common area and knows of a dog's viciousness may face a negligence claim, one based on carelessness, when the dog attacks there. That holding drew on the Residential Landlord and Tenant Act's common-area safety duty in Section 27-40-440. Frost Law Group represents guests in injury claims against apartment complexes when the complex's conduct is part of the harm. In that setting, the landlord's own liability coverage may respond.
A Landlord Who Took Charge of the Tenant's Dog
The bite statute reaches anyone keeping or caring for the dog, and a landlord can land in that group. Clea applied the test from Harris v. Anderson County Sheriff's Office. That test asks whether a property owner controlled the premises and took responsibility for the dog's care. In Clea, the landlord had exclusive control of the common area, and he knew the dog was chained there. The dog had lived in that spot continuously, and those three facts gave the Court a jury question on keeping. What a landlord actually did around a dog can bring the landlord's policy into the claim.
Does a Lease's Pet Rule Make the Landlord's Insurer Pay?
Usually not, under Gilbert v. Miller. A visitor bitten at an apartment complex pointed to a lease term restricting tenants' pets. The Court of Appeals read that provision as protecting the property from damage by pets, not as protecting guests. It held the visitor was not a third-party beneficiary, meaning someone the contract was written to benefit, so the clause created no duty. Other lease terms or the landlord's own conduct can still change the answer, so the whole lease deserves a read.
What an Adjuster Asks For and How a Summerville Dog Bite Attorney Responds
An adjuster's early requests after a bite are fairly predictable. Expect questions about where you stood, what you did beforehand and how badly you were hurt. You may also get a request for a recorded statement and a signed medical release, sometimes broad enough to reach years of unrelated records. Dog bite insurance claim lawyers in Summerville can often answer those requests in writing instead. The emergency chart carries weight early, whether it comes from HCA Healthcare Summerville Hospital, the 174-bed hospital on Midland Parkway, or another emergency room.
Jack C. Frost put in fourteen years with the Summerville Police Department and the Charleston County Sheriff's Office. Over those years he learned how an investigator assembles a file and how a spoken account turns into a written report. That experience helps Frost Law Group judge what goes to an adjuster, in what form and at what point. Any insurer's valuation rests on the injury, the records and the policy, and no lawyer can promise where it lands.
Recorded Statements About the Seconds Before the Bite
Adjusters' questions often track the statute's defenses. Section 47-3-110 stops applying when a victim's provoking or harassing of the dog was the proximate cause of the attack. Lawyers use that phrase for a direct and foreseeable cause. It also protects only someone in a public place or lawfully in a private one. A casual answer such as "I reached over the gate to pet him" can become the start of a provocation argument. A lawyer can prepare a client before any statement, or supply the facts in writing instead.
Finding the Liability Limit on a Homeowner Policy
The limit shapes the whole claim, yet homeowner insurers do not always volunteer it. A modest limit against a serious scar changes how a claim is presented and what a sensible resolution looks like. Frost Law Group can use different tools depending on whether a lawsuit has been filed. The right tool depends on timing and on how cooperative the owner is, which a lawyer weighs claim by claim.
Asking for Homeowner Limits Before a Suit
Before any suit, the information usually comes from the owner or the insurer by agreement. A neighbor on good terms with you may simply agree to help. A request made politely and in writing leaves a record of what was asked and what came back.
The Owner's Declarations Page
The simplest route runs through the owner. The declarations page shows the liability limit, the medical payments amount and any added coverage. An owner who wants the claim resolved can share it directly, which can save everyone a round of letters.
Why the Auto Limits Statute Does Not Apply
Section 38-77-250 makes insurers providing automobile coverage disclose limits after a proper written request from a claimant's lawyer. They have 30 days to answer. The statute's text speaks only of automobile coverage and private passenger policies, so a homeowner insurer has no matching duty under it.
Discovery of the Policy After a Suit Is Filed
Once a suit is pending, South Carolina's civil procedure rules open the policy to discovery, the formal exchange of information between the parties before trial. Rule 26(b)(2) lets a party learn the existence and contents of any insurance agreement that may pay part or all of a judgment. The same rule says that disclosure does not by itself make the policy admissible at trial. That right matters most when an insurer will not share its limit voluntarily.
When an Adjuster Misstates the Policy or Stalls
Section 38-59-20 lists improper claim practices, and several name third-party liability claims directly. They include knowingly misrepresenting pertinent facts or policy provisions to a third-party claimant. They also include failing to attempt a prompt, fair settlement in good faith once liability has become reasonably clear. The statute reaches only conduct frequent enough to show a general business practice, not a single misstep on one file. It works as an administrative rule, which the Director of Insurance enforces after notice and a hearing. A pattern of those practices can go to the Department's Office of Consumer Services, which takes complaints about insurers and adjusters.
The Three-Year Deadline While an Adjuster Reviews the File
Section 15-3-530 sets the general window for a bite suit at three years. Nothing in that section stops the count because an insurer is still evaluating the claim. Section 15-3-535 adds a discovery rule, so the three years run from the day a bitten person found out about the claim, or reasonably should have. An open insurance claim does not by itself preserve the right to sue, so the deadline needs tracking from the start.
Dog Bite Insurance Claim Lawyers in Summerville Who Keep the Claim Neighborly
You can stay on good terms with a neighbor and still ask the neighbor's insurer to pay for your care. Frost Law Group's dog bite insurance claim lawyers in Summerville build claims that way, aimed at the policy rather than the person. Start by asking the owner for the insurer's name and the declarations page. Keep your emergency paperwork, and hold any medical release until a lawyer has read it.
Tara and Jack share a single office, and calls reach one of them instead of an outside call center. A free, confidential consultation with either of them leaves the decision to hire the firm entirely with you.
Meetings take place at 128 Linwood Lane, Summerville, SC 29483. Bring the owner's name, the date of the bite and any letter an insurer has already sent.
Phone (843) 419-6653, or write to the Frost Law Group office online with a sentence or two about the bite, the dog and its owner.
The attorneys at Frost Law Group
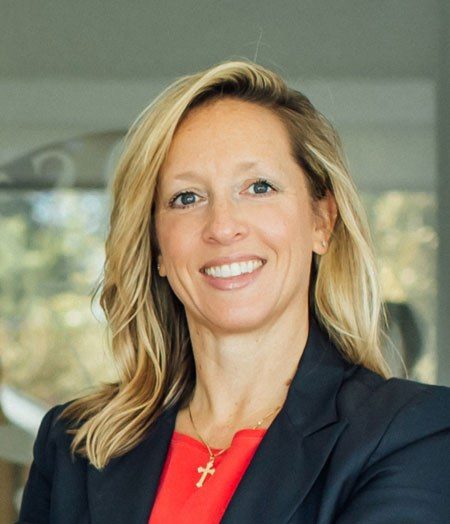 Tara L. FrostAttorney at Law · Personal injuryTara L. Frost focuses on personal injury, car accident and truck accident claims. A lifelong resident of the tri-county area, she meets clients at the Linwood Lane office in Summerville.
 Jack C. FrostAttorney at Law · Former Summerville police officer and Charleston County Sheriff's Office detectiveJack C. Frost spent fourteen years in law enforcement with the Summerville Police Department and the Charleston County Sheriff's Office before he practiced law.