Is South Carolina an At-Fault State
- Free consultation
- No fee unless we win
- Available 24/7
Is South Carolina an at-fault state? Yes. South Carolina runs a tort system, which means the driver who causes a crash answers for the harm, usually through that driver's liability insurance. An injured person claims against that coverage instead of a no-fault policy. Shared fault can shrink the claim or end it.
The South Carolina Department of Insurance says the state "implements a tort system." It names liability and uninsured motorist coverage as the two purchases the law requires. Section 38-77-144 adds that South Carolina mandates no personal injury protection, or PIP, the no-fault benefit that pays without regard to blame. So the first question after a crash is who caused it, and that answer steers every claim that follows.
Tara L. Frost focuses on injury claims from car crashes at Frost Law Group, the Summerville practice she shares with her husband, Jack C. Frost. Jack was her Summerville High School sweetheart. Later, both earned law degrees in Charleston, at the Charleston School of Law. Together they can review a crash the way an insurer will, starting with the collision report, the photos and each driver's declarations page.
Call Frost Law Group at (843) 419-6653 to sort out whose insurance should pay for your crash. The consultation is private, free of charge, and binds you to nothing.
On this page
Whose Insurance Pays First After a South Carolina Crash
The at-fault driver's liability insurer is the main payer for an injury claim, because that policy exists to cover people its driver hurts. Frost Law Group can build the claim around that policy once the evidence shows who caused the collision. Say a driver rolls through a stop sign on Central Avenue and strikes your car. Your medical bills become a claim against that driver's bodily injury coverage, and your car becomes a claim against the property damage coverage.
What if the at-fault driver borrowed the car? Section 38-77-142 requires every liability policy to cover the named insured and anyone driving with the named insured's express or implied consent. So a friend's borrowed SUV usually brings the policy on that SUV into the claim, subject to its terms. Section 38-77-142(B) also limits one coverage defense. When the insurer actually knows someone served its insured with a suit, the insured's failure to forward the papers is no defense for the insurer. That rule holds only if the insured otherwise cooperates and does not prejudice the insurer.
The Department of Insurance lists pain and suffering, lost wages and medical expenses among the losses a bodily injury claim may include. None of that money arrives automatically. An insurer usually weighs the report, the photos and the statements before it accepts fault. The value of any claim depends on evidence a lawyer has to review.
Is South Carolina an At-Fault State for Property Damage Too?
Yes. Property damage liability pays for what the at-fault driver damages. The Department of Insurance says that reaches buildings, walls, fences and equipment as well as cars. Section 38-77-140 sets that coverage at $25,000 per accident at minimum.
Section 38-77-330 keeps a pending injury claim from holding up payment for the damaged car. Under Section 38-77-230, paying for the damaged property is not an admission of liability on any other claim from the crash. So the repair claim can move ahead while the medical side is still developing.
When Your Own Policy Pays Before Fault Is Settled
Some coverage on your own policy does not depend on blaming anyone. Medical payments coverage, called med pay, is optional in South Carolina, and Section 38-77-144 groups it with no-fault coverage. That statute also bars assignment or subrogation of med pay, so the insurer cannot collect it back from the driver at fault. Collision coverage is optional too, though the Department of Insurance notes a lender may require it.
Health insurance often pays medical bills while the fault question stays open. Section 38-71-190 allows a health policy written in South Carolina to include a right to recover from your injury settlement. That recovery cannot exceed the benefits the plan paid. Whether your plan falls under that statute depends on how and where it was written.
What Are South Carolina's Minimum Liability Limits
South Carolina's minimum liability limits are $25,000 for bodily injury to one person and $50,000 for bodily injury to two or more people in one accident. The property damage floor is $25,000, so the whole pattern reads 25/50/25. Section 38-77-140 sets those numbers for each insured vehicle, and they also set the floor for the UM coverage on your own policy. Frost Law Group can compare them with the medical bills to see whether one policy can cover the loss.
Nothing stops a driver from buying more, and Section 38-77-140 says so directly. SCDMV also will not register a car until the owner shows the required insurance, under Section 56-10-10. Whether the other driver's limits are enough depends on the injuries and the proof, which a lawyer has to weigh case by case.
How Do Several Injured People Share the $50,000 Limit?
Picture a pickup crossing the center line on Orangeburg Road and hitting a car with three people inside. If the pickup's policy carries only the minimum, all three share one $50,000 bodily injury limit. No single passenger can collect more than $25,000 from it, because the statute makes the larger figure subject to the per-person cap. How the rest divides depends on each person's injuries and records.
Can You Learn the Other Driver's Limits Before Settling?
Yes, through a lawyer. A claimant's lawyer can use Section 38-77-250 to demand the coverage figures in a sworn request that includes the incident report. The carrier must reply under oath within 30 days, naming itself, every insured and the limits. It can simply produce the declarations page instead. The duty does not reach fleet, umbrella or excess policies, so more coverage may exist than the first answer shows.
What If the At-Fault Driver Has No Insurance
If the at-fault driver has no insurance, your own uninsured motorist coverage pays what you could have recovered from that driver, up to its limits. Section 38-77-150 makes that coverage, called UM, a required part of every auto policy delivered in this state. Section 38-77-30 also counts some insured cars as uninsured, such as one whose insurer successfully denies coverage or goes insolvent. Frost Law Group represents people in uninsured motorist coverage disputes with their own carriers when the other driver had nothing to offer.
UM limits start at the same 25/50/25 floor, with no less than $25,000 of coverage for your damaged property. A policy can leave the first $200 of that loss uncovered. Fault still matters here. Your carrier may answer a lawsuit in the uninsured driver's name and dispute both fault and damages.
A UM lawsuit follows its own procedure. Under Section 38-77-150, copies of the pleadings must reach the UM carrier, and the carrier may appear within 30 days of service. Frost Law Group can serve the carrier, so the UM claim moves forward in the same suit.
Penalties for Driving Without Insurance
Under Section 56-10-520, an owner who drives or lets someone drive an uninsured car, or a driver who knows it is uninsured, commits a misdemeanor. A first conviction can mean a $100 to $200 fine or 30 days behind bars. On notice of a violation, SCDMV suspends the owner's license, registration and plates until the owner pays a reinstatement fee the Department of Insurance sets each year. A driver who does not own the car loses the license for at least 30 days.
Until July 1, 2024, Section 56-10-510 allowed an owner to register a car without insurance by paying a fee. 2023 Act No. 51 turned that section into a reserved placeholder, so the fee route no longer exists.
Does Underinsured Coverage Help When the Driver Carries Too Little?
It can. A driver is underinsured when the policy meets the minimum but falls short of your damages. Underinsured motorist coverage, or UIM, can pay the difference from your own policy. Insurers must put UIM on offer under Section 38-77-160, yet the Department of Insurance says buying it is your choice. That section also voids any UIM term requiring your carrier's permission before you settle with the driver who caused the crash.
Ask a Summerville Car Accident Attorney About Fault in Your Crash
Is South Carolina an at-fault state even when your own UM carrier pays the claim? Yes. That carrier owes only what you could have recovered from the driver who caused the crash. Fault stays at the center of every file.
Tara L. Frost and Jack C. Frost can sort out which policy answers first and what each one holds. Have your declarations page ready, along with the collision report number and a photo of the other driver's insurance card. Frost Law Group meets clients at 128 Linwood Lane, Summerville, SC 29483. When you phone the office, you talk with a lawyer and not an answering service.
Ask Frost Law Group for a free, confidential consultation about the fault questions in your claim. Call (843) 419-6653, or send Tara and Jack Frost a message online with the crash date and your insurer's name.
The attorneys at Frost Law Group
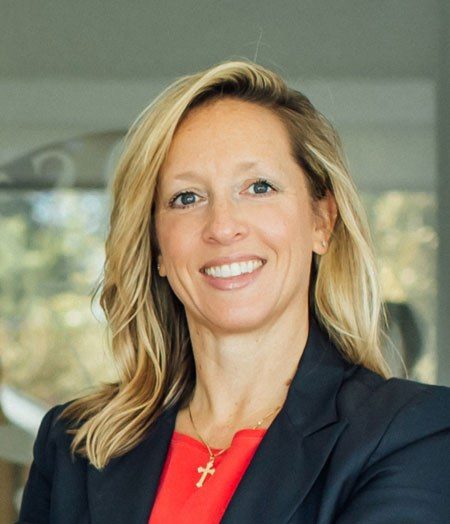 Tara L. FrostAttorney at Law · Personal injuryTara L. Frost focuses on personal injury, car accident and truck accident claims. A lifelong resident of the tri-county area, she meets clients at the Linwood Lane office in Summerville.
 Jack C. FrostAttorney at Law · Former Summerville police officer and Charleston County Sheriff's Office detectiveJack C. Frost spent fourteen years in law enforcement with the Summerville Police Department and the Charleston County Sheriff's Office before he practiced law.