Should I Talk to the Other Driver's Insurance Company
- Free consultation
- No fee unless we win
- Available 24/7
Should I talk to the other driver's insurance company? You may, but no South Carolina statute requires you to give that company a recorded statement. Report the crash to your own insurer, because your policy likely requires it. With the other adjuster, keep to basic facts, and have a lawyer review any release or offer before you sign.
South Carolina's auto insurance statutes sit in the South Carolina Code's auto insurance chapter, Title 38, Chapter 77, which covers minimum limits, coverage offers and claim handling. Nothing in it tells an injured claimant to sit for a taped interview with the at-fault driver's carrier. Title 38, Chapter 59, which governs claim handling practices, is silent on that too. Duties to your own company come from your policy, which is a contract rather than a statute.
Frost Law Group represents people hurt in Lowcountry car crashes and can step in once the other driver's adjuster starts calling. From mid-2022 until August 2025, Dorchester County had Tara L. Frost on its magistrate bench. That work gave her a courtroom view of how judges weigh credibility, including a witness who tells a story twice. The perspective helps when the firm weighs what a client should put on the record.
Before you return the adjuster's call, reach Frost Law Group at (843) 419-6653. The consultation stays confidential, carries no charge and commits you to nothing.
On this page
Do You Have to Give a Recorded Statement
No statute makes you give the other driver's insurer a recorded statement. A recorded statement is a phone interview the adjuster tapes. It usually covers how the crash happened, how you feel and where you got treatment. Frost Law Group takes on crash claims where that request arrives early, sometimes before a doctor has finished evaluating the injury.
Keep in mind whose side the adjuster is on. The Department of Insurance auto insurance FAQ explains that a liability insurer has a duty to provide a lawyer when someone sues its own policyholder for careless driving. So the company calling you may one day defend the driver who hit you. Its adjuster can be polite and professional while still working for the other side.
What the Insurer Does With a Taped Interview
Picture a side impact at Dorchester Road and Bacons Bridge Road, where the SCDPS Fact Book recorded 41 collisions in 2024. The next morning your shoulder aches, but no orthopedist has examined it yet. A taped "I'm fine, just sore" captures that morning and nothing after it. The recording then goes into the carrier's file, where an adjuster can hold your words up next to the officer's report and your chart. Gaps between those accounts can become reasons the company gives for a lower number.
Can You Share Basic Facts and Decline the Rest?
Yes. You can confirm your name, contact details, the vehicle and where the car sits for an inspection. You can also turn down a taped interview about fault or injuries and ask the adjuster to put questions in writing. Honest answers matter, yet answers given before the facts are in can leave an incomplete record. Giving the adjuster your lawyer's name and stopping there keeps later statements consistent.
A short reply usually covers it. You might say you are still being treated, that you will not do a taped interview, and that written questions will get a written answer. Write down the adjuster's name, the company and the claim number before you hang up.
Read the Collision Report Before Any Taped Call
The officer's report is the document an adjuster may quote back to you, so read it first. Copies cost $10 through SCDMV, and you can order one online, in person at a branch, or with a mailed FR-50. The Summerville Police Department points requesters to CrashDocs, an outside website. If the report gets a lane, a direction or a witness wrong, you want to know that before an adjuster asks you to agree with it.
Section 56-5-1290 keeps those required reports from proving anyone's negligence when a damages case goes to trial. Adjusters may still lean on them while a claim is open, so Frost Law Group can check the report against photos and witness accounts.
Should You Sign a Medical Records Release
Not before you know exactly what it reaches. The picture often shifts once a release form shows up in the mail. A medical records release, often called an authorization, lets the insurer pull charts straight from your doctors and hospitals. A broad form may name no provider and set no date range. That can open years of records that have nothing to do with the wreck.
Your injury claim does rest on medical proof, so the records will come out in some form. The real question is scope. Suppose you went to an emergency department the night of the crash. An orthopedic surgeon then followed up. Those crash visits document the injury. A knee visit from years earlier may only hand the insurer an argument about a condition that predates the wreck.
Frost Law Group can gather the crash-related charts and send those, instead of opening every file you have. The firm also handles vehicle and rental claims after a crash you did not cause, which usually move apart from the medical questions.
What Do You Owe Your Own Insurance Company
You owe your own insurer whatever your policy requires, which likely includes prompt notice of the crash and reasonable cooperation. Those duties come from the contract, not from a statute. So read the conditions section of your policy, or have a lawyer read it with you. Never mislead your own company, because honest cooperation protects coverage you may need.
Pull your own declarations page before that first report. It lists what you carry, including uninsured and underinsured motorist limits and any med pay. Those lines tell you which parts of your own policy might pay if the other driver's coverage falls short.
Your own policy may end up paying part of the loss. Frost Law Group can explain the steps to take after a South Carolina car crash, and reporting to your own carrier is one of them.
If you carry med pay, Section 38-77-144 shields those benefits from subrogation and setoff. That means your insurer cannot collect them back from the at-fault driver or subtract them from another recovery. Before your insurer takes a general release in exchange for med pay or uninsured motorist benefits, Section 38-77-260 requires an approved disclosure form and a wait of at least three days.
Uninsured Motorist Claims and Section 38-77-200
Uninsured motorist coverage pays, up to its limits, what you could have collected from a driver with no insurance. Section 38-77-200 limits what that part of your policy may ask of you. It cannot force arbitration. Beyond the statute and the state's approved form, the only thing it may demand is that you establish the uninsured driver's legal liability. It also may not stop you from hiring a lawyer or filing suit. If you do sue, Section 38-77-150 lets your own carrier defend in the uninsured driver's name.
Underinsured Motorist Claims and Notice of Suit
Underinsured motorist coverage can help once the other driver's liability limits run out before your losses do. What you owe that carrier under the statute is mostly notice. If you sue the at-fault driver, Section 38-77-160 requires you to serve your underinsured carrier with the suit papers, and it then has 30 days to appear. The same section bars any policy clause requiring the carrier's consent before you settle. Your policy may add its own notice terms, so read them before settlement talks begin.
What About a Quick Settlement Offer
Settlement offers come paired with a release, and signing that release generally ends the injury claim for good. A release is a signed promise to drop every claim it names in exchange for the payment. After you sign, a new diagnosis or a later surgery usually cannot reopen it. The filing window for most South Carolina injury claims is three years, set by Section 15-3-530. Nothing in that statute forces a quick signature.
Whether an early offer is fair depends on the medical picture, the limits available and who has a claim on the money. Frost Law Group can review what a car accident claim may be worth once treatment shows the full injury. No lawyer can promise a figure, and the answer depends on the evidence.
Slow handling has a regulator too. Section 38-59-20 lists as an improper claim practice an insurer's failure to try in good faith to settle promptly and fairly once liability is reasonably clear. The Director of Insurance enforces it when the conduct amounts to a general business practice, and the Department takes consumer complaints.
Who Has a Right to Be Repaid From a Settlement?
Several payers may have a stake before you see a dollar. Section 43-7-420 gives SCDHHS, which runs Medicaid in South Carolina, the right to recover what Medicaid spent on crash care. Section 43-7-440 ranks that right ahead of any other reimbursement, subrogation or indemnity right of a third party or the recipient. Federal law requires repayment of Medicare's conditional payments out of a liability settlement. A health insurance policy issued in South Carolina may claim back only the benefits it already paid, under Section 38-71-190.
Can SCDMV Tell You Whether the Other Driver Had Insurance?
Yes, and the adjuster is not your only source on that question. Section 56-5-1340 lets SCDMV tell someone who suffered injury or property damage what the filed reports show about insurance. That answer points you toward the right claim, whether against the driver's carrier or your own policy.
The policy limits themselves usually come out through a lawyer's sworn request under Section 38-77-250. Knowing that ceiling helps you judge whether an offer is an opening number or the whole policy.
Talk With a Summerville Car Accident Attorney Before You Call Back
An adjuster's voicemail can sit until you have a plan. The question "Should I talk to the other driver's insurance company?" deserves an answer that fits your crash, your coverage and your injuries. Frost Law Group can review the letters, forms and offers you have received. The firm can then explain what each one asks you to give up.
Bring the adjuster's name, the claim number and any paperwork the insurer mailed you to 128 Linwood Lane, Summerville, SC 29483. Tara and Jack Frost see clients there. A phone call goes to one of them rather than to a call center, and the consultation is free and confidential.
Ring (843) 419-6653 today, or send the office a message online before your next conversation with the carrier.
The attorneys at Frost Law Group
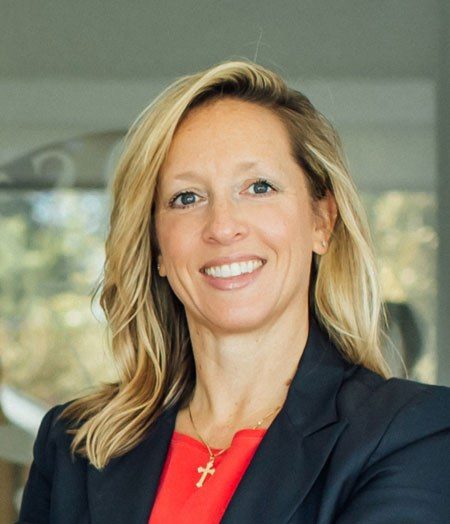 Tara L. FrostAttorney at Law · Personal injuryTara L. Frost focuses on personal injury, car accident and truck accident claims. A lifelong resident of the tri-county area, she meets clients at the Linwood Lane office in Summerville.
 Jack C. FrostAttorney at Law · Former Summerville police officer and Charleston County Sheriff's Office detectiveJack C. Frost spent fourteen years in law enforcement with the Summerville Police Department and the Charleston County Sheriff's Office before he practiced law.