How Much Is My Car Accident Case Worth
- Free consultation
- No fee unless we win
- Available 24/7
How much is my car accident case worth? No reliable answer comes as a number before someone reviews the facts. In South Carolina, value turns on four things. They are your proven losses, your share of fault, the insurance available, and any repayment claims against the recovery.
Coverage floors come from the motor vehicle insurance statutes in Title 38, Chapter 77. Under Section 38-77-140, each policy must carry at least $25,000 for one injured person and $50,000 for all the people hurt in a single crash. The Department of Insurance says a bodily injury claim may reach lost wages, medical expenses, and pain and suffering. No statute prices a particular injury, so any figure for your claim waits until a lawyer has read the records.
At Frost Law Group, the married attorneys Tara L. Frost and Jack C. Frost handle car crash injury claims. Tara is a former Dorchester County Magistrate Judge. Presiding there, she saw how much weight evidence, preparation and credibility carry with a judge. The Frosts bring that courtroom view to a claim file before anyone talks about money.
Call Frost Law Group at (843) 419-6653 to walk through the parts of your claim. That conversation is confidential, carries no charge and creates no duty to hire anyone.
On this page
What Damages Make Up a Car Accident Claim
A car accident claim combines three kinds of loss. There are economic losses you can document, noneconomic losses such as pain, and damage to your vehicle. Frost Law Group can sort each loss into its group before anyone discusses a figure. Economic losses start with medical bills, both paid and still ahead. Wages missed while you healed belong there too.
Picture a driver rear-ended while stopped on Dorchester Road at Old Trolley Road. The 2024 SCDPS Fact Book tied that junction to 53 collisions. She spends a night at HCA Healthcare Summerville Hospital and misses shifts at work.
Her bills and lost pay make up the economic side. Her trouble lifting her child and sleeping at night is noneconomic, and no receipt proves it. A jury would weigh each side from her records and testimony. A lawyer reviews both before saying anything about value.
Some injuries change the rest of a life, and then future care can outweigh every bill already paid. Frost Law Group handles claims for catastrophic injuries from crashes. In those cases, a life care plan often documents the future needs.
What the Damaged Vehicle Adds to the Claim
The car follows its own measure. Newman v. Brown, a South Carolina Supreme Court decision from 1955, measured car damage by lost market value. The court compared the value just before the crash with the value just after it. It then treated loss of use during a reasonable repair period as a separate item. The Department of Insurance says the at-fault carrier owes reasonable and necessary loss of use, often a rental.
Can Punitive Damages Add to a Crash Claim?
Only in narrow cases. Punitive damages punish a wrongdoer instead of paying back a loss. Section 15-32-520 permits them only when clear and convincing evidence shows the harm flowed from willful, wanton or reckless conduct. Most awards then face a cap in Section 15-32-530, set at the greater of a set multiple of the compensatory award or a dollar figure adjusted yearly for inflation.
Listed situations raise or remove that cap. One is a driver whose judgment the court finds substantially impaired by alcohol or non-prescribed drugs. Nobody can promise punitive damages in any case.
How Does Fault Change the Number
Fault lowers an award by the injured person's percentage of blame. It wipes out recovery when that percentage is greater than the other driver's share. That rule traces to the state Supreme Court's 1991 ruling in Nelson v. Concrete Supply Co. For crash claims where both drivers made mistakes, Frost Law Group treats the fault split as seriously as the injury.
Say a pickup turns left across Bacons Bridge Road while you drive a little over the limit. A jury might put most of the fault on the turning driver and a small share on you. Under Nelson, your award would then shrink by that small share. Nobody can forecast where a jury will draw the line, because it rests on proof a lawyer has to test.
Adjusters know the rule well. An argument that you carry a larger share is also an argument for a smaller payment. Photos, witness names and the damage pattern on both cars give Frost Law Group something concrete to answer with.
Can the Insurer Cut the Claim Because You Were Unbuckled?
Not through a courtroom. Under Section 56-5-6540(C), going unbuckled does not make you negligent per se, which would mean automatic proof of carelessness. Nor does it count as contributory negligence, your own share of the fault.
The same subsection keeps evidence of the violation out of a civil trial. That rule covers the driver and every occupant the article requires to buckle up. Section 56-5-6460 gives child restraint violations parallel treatment. An adjuster may still raise the belt in early talks, and Frost Law Group can cite the statute in reply.
When Several Drivers Share the Blame
Section 15-38-15 has limited what a less-blameworthy defendant owes ever since July 1, 2005. A defendant under 50% at fault owes only its own slice of the damages. A defendant at 50% or more may answer for the entire award. The newer Act No. 42 of 2025 lets jurors also weigh wrongdoers nobody sued, but only in claims arising after the first day of 2026. The crash date decides which version governs a three-car pileup on Interstate 26.
Why Do Policy Limits Matter So Much
Policy limits matter because an insurer's payment usually stops at the limit, whatever the injuries are worth. The Department of Insurance tells policyholders that a judgment or settlement beyond the limits leaves the driver owing the difference. Whether a driver can actually pay it is a separate, practical question.
Imagine a driver carrying only the state minimum. She runs a red light on North Main Street and breaks your pelvis. If your losses climb far past $25,000, that one policy cannot cover them. Underinsured motorist coverage on your own policy may pay beyond the other driver's limit, up to your own UIM limit. Every insurer must put it on offer, per Section 38-77-160, yet buying it is your call.
Frost Law Group handles UM and UIM claims against a person's own insurer when the at-fault coverage runs short. Every declarations page in your household may matter here, and a lawyer checks them all before discussing value.
Umbrella and Excess Coverage Beyond the Basic Limits
Under the limits disclosure statute, Section 38-77-250, a claimant's lawyer may request a carrier's limits under oath, though that duty skips fleet, umbrella and excess coverage. An at-fault driver's umbrella policy may not appear in that sworn answer, so a lawyer may need to raise it another way. Section 38-77-161 adds that an umbrella policy need not include uninsured or underinsured coverage. Your own umbrella policy may not extend your UM or UIM protection, and its terms decide.
When a Government Vehicle Caused the Wreck
The South Carolina Tort Claims Act covers claims against a state agency, county, town or other political subdivision. Its ceilings, found in Section 15-78-120, are $300,000 per person and $600,000 per occurrence. The act also rules out punitive damages and interest before judgment.
Picture a county dump truck drifting into your lane on US 78 near St. George. Your own UIM may matter there, because Section 38-77-160 lets offered underinsured coverage reach damages beyond a statutory cap. Whether it reaches your loss depends on the policy language and the facts of the crash.
Who Gets Repaid From a Settlement
Medicaid, Medicare and some health insurers can recover what they paid for crash care. So the amount you keep often differs from the amount an insurer pays. Under South Carolina's Medicaid recovery statutes in Title 43, Chapter 7, the law deems a recipient to have assigned that repayment right to SCDHHS. Section 43-7-440 makes the department's right superior to other reimbursement and subrogation rights held by third parties or the recipient. The department may also trim its claim by 25% when the person it covered has hired a lawyer.
Medicare's payments for crash care come with a federal condition, reimbursement from any liability recovery. Under Section 38-71-190, a South Carolina health policy may seek back only the benefits it paid. That insurer also bears attorneys' fees and costs from its own recovery. A lawyer checks, plan by plan, whether that statute covers a self-funded employer plan.
Med pay stands apart. Section 38-77-144 forbids subrogation of that coverage, meaning the insurer cannot take its payment back out of your recovery.
Take a Ladson resident whose Medicaid card covered an ambulance ride to Trident Medical Center. The Department of Public Health lists Trident as an Adult Level II trauma center. Any settlement would first have to account for what Medicaid spent. Frost Law Group can ask each payer for its figure early, so the net amount is clearer before anyone signs.
Why Online Settlement Averages Mislead
Averages mislead because they strip away the facts that set value. Those facts are the losses, the fault split, the coverage and the repayment claims. Anyone who searches “how much is my car accident case worth” gets figures drawn from other people's crashes. An online figure rarely says which state's law applied. It seldom says whether the payer was a driver with minimum limits or one with far higher coverage.
Two Summerville neighbors with the same broken wrist show the problem. A driver with minimum limits hit the first, and she carried no UIM of her own. A driver whose policy carried far higher limits hit the second, and the proof of fault was clear. Their results could differ widely for reasons unrelated to the wrist. Frost Law Group studies those differences in the file itself rather than a national figure.
Caps skew averages too. South Carolina's statutory limit on pain-and-suffering awards is written for medical malpractice claims. The Tort Claims Act caps apply only when a government defendant is involved.
A blended average can mix those claims with ordinary crash cases. It may also fold in punitive awards, which require clear and convincing proof. A number built that way says little about your claim, and only a review of your own records can say more.
Ask a Summerville Car Accident Lawyer What Drives Value in Your Case
Gather the paper trail before anyone quotes a figure. Medical bills, pay stubs, repair estimates and both drivers' insurance cards all belong in it. So does any letter from Medicaid or a health plan. Together they answer much of the question, “How much is my car accident case worth?”
The two Frost attorneys work from 128 Linwood Lane, Summerville, SC 29483. Calls go to Tara and Jack themselves, not to an outside answering service.
Ask for a free, confidential consultation, and they can explain which factor weighs most in your file. No lawyer can promise a result. You can still leave knowing what your claim depends on.
Phone (843) 419-6653 whenever your treatment schedule allows, or send Frost Law Group a message online.
The attorneys at Frost Law Group
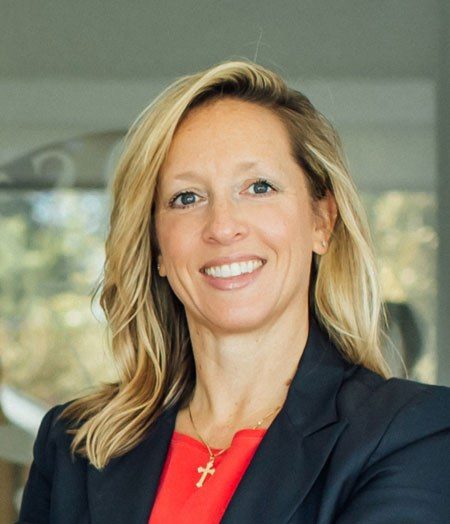 Tara L. FrostAttorney at Law · Personal injuryTara L. Frost focuses on personal injury, car accident and truck accident claims. A lifelong resident of the tri-county area, she meets clients at the Linwood Lane office in Summerville.
 Jack C. FrostAttorney at Law · Former Summerville police officer and Charleston County Sheriff's Office detectiveJack C. Frost spent fourteen years in law enforcement with the Summerville Police Department and the Charleston County Sheriff's Office before he practiced law.