What Happens If a Car Accident Was Your Fault
- Free consultation
- No fee unless we win
- Available 24/7
What happens if a car accident was your fault? Your liability insurance pays the claims of the people you hurt, up to your limits. Your policy may also provide a lawyer if someone sues you. You may still recover for your own injuries, as long as the other driver was at least as careless as you were.
The coverage rules sit in Section 38-77-142 of the South Carolina Code. It says an auto liability policy must shield the named insured, and anyone driving with permission, from liability for negligent driving. Section 38-77-140 sets the smallest amounts at 25/50/25. Any duty to defend you comes from the policy's own language. Check the policy form and the declarations page, the summary sheet that lists your coverages and limits.
At Frost Law Group, a driver who may share the blame still gets a full look at his or her own injury claim. Jack C. Frost brings fourteen years of police work to that review. He served with the Summerville Police Department and the Charleston County Sheriff's Office. He knows what a collision report says about each driver and what it leaves out. Together with Tara L. Frost, he can separate the questions about your coverage from the questions about your injuries.
Call Frost Law Group at (843) 419-6653 if you were hurt in a crash you may have caused. A consultation is free and private, and it does not obligate you to hire anyone.
On this page
Does Your Liability Insurance Pay the Other Driver
Yes. Your bodily injury and property damage liability coverage pays the other driver's valid claims, up to the limits on your declarations page. Frost Law Group can start with that page, because it shows what coverage stands behind you. Say you misjudge a gap while turning onto Dorchester Road and strike an oncoming pickup. The pickup driver's medical bills and repair costs become claims against your coverage.
Your insurer may pay for the pickup's repairs before anyone settles the injury questions. Section 38-77-230 says that payment is not an admission of liability by you. Nor does it show your insurer recognizing liability on any other claim from the same crash. A check for a dented fender does not decide who caused the wreck.
According to the Department of Insurance, when a court judgment or settlement tops your limits, you have to pay the difference. How that plays out depends on the policy terms and the facts, which a lawyer reads before anyone assumes the answer. Frost Law Group can also explain how South Carolina's at-fault insurance rules decide which policy answers first.
Will Your Insurer Pay for Your Own Car?
Only if you bought collision coverage, which the South Carolina Department of Insurance describes as optional. Collision pays for physical damage to your car when it hits another car or an object, less your deductible. Without it, your liability coverage protects other people's property and leaves your own car uncovered. A lender may have required collision when you financed the car, so check the declarations page before assuming either way.
Can a Passenger in Your Car Claim Against Your Policy?
Usually a passenger hurt in a crash you caused may claim against your liability coverage, the same as the other driver. If the other driver shared the blame, the passenger may also claim against that driver's coverage. A relative who lives with you is a harder case. Whether that relative can claim against your own liability policy depends on the policy and on South Carolina insurance law, which a lawyer checks before advising the family.
What If You Are Sued
If someone sues you, send the summons and complaint to your insurer right away, as the Department of Insurance advises. Your policy probably obliges you to give prompt notice and to cooperate. Section 38-77-142(B) offers a cushion if that step slips. An insurer that already knows about the suit cannot use your failure to forward the papers, by itself, as a defense. That holds as long as you otherwise cooperate and cause the insurer no prejudice.
When a suit accuses you of careless driving, the Department of Insurance says your company must supply a defense lawyer. Although the company pays that lawyer, the Department says the lawyer's ethical duty is to you. Frost Law Group's work centers on your own injury claim, a separate matter from that defense.
The size of the claim shapes where it goes. Claims worth $7,500 or less fit within a magistrate's civil limit in Section 22-3-10. A small fender claim against you could land there. Bigger injury claims belong in the circuit court, whose civil docket is the Court of Common Pleas.
Section 15-3-530 gives the injured driver three years to file most injury claims. Section 15-3-20(B) treats a suit as started on filing only when service follows within 120 days. The injured driver's lawyer can also demand your coverage limits under Section 38-77-250. Your carrier then has 30 days to reply with a sworn statement. None of that means a suit will come, and the odds of one turn on the injuries, the evidence and the coverage.
Can You Still Recover for Your Own Injuries
Yes, you can still recover for your own injuries if your share of the fault is no larger than the share the other driver carries. The award then drops by your percentage. The South Carolina Supreme Court adopted that test in 1991, in Nelson v. Concrete Supply Co. So what happens if a car accident was your fault depends heavily on how much of the fault was yours. Frost Law Group handles shared fault injury claims for drivers who made a mistake but were not the only one who did.
The same math runs in both directions. Suppose a jury finds you 40% at fault and the other driver 60%. Your claim survives at 60% of your damages, and the other driver, being more at fault, recovers nothing from you. If the numbers flip, you recover nothing, and the other driver's claim against you shrinks by that driver's own 40%.
Picture a driver ticketed for failing to yield on Central Avenue while the other car came through too fast. The speed statute, Section 56-5-1520, asks more than obedience to the sign. Speed also has to fit the traffic, the weather and the hazards of that moment. A jury could find the ticketed driver partly responsible and the speeding driver more so. The split depends entirely on the proof, so no one can promise where it lands.
Does the Traffic Ticket Decide Fault in Your Injury Claim?
No, not on its own. Section 56-5-6160 covers convictions under the traffic chapter, Title 56, Chapter 5. Evidence of such a conviction cannot come into any civil action, including an injury suit. How that rule treats a paid ticket or a guilty plea is a question for a lawyer.
Section 56-5-1290 separately keeps the required crash reports from proving either driver's negligence at a damages trial. The injury claim turns on evidence of what each driver actually did. Photos, witnesses and the damage to each vehicle carry that weight.
What Your Own Policy May Pay Regardless of Fault
Medical payments coverage is optional, and Section 38-77-144 lists it among the no-fault coverages an insurer may sell. If you bought med pay, it may help with medical bills whether or not you caused the crash. The policy terms control. If the other driver shared the fault but carried too little insurance, underinsured motorist coverage on your policy may also apply. Insurers must offer that coverage, though nobody has to buy it.
Should You Admit Fault at the Scene
No, you do not need to announce who caused the crash, and you should never hide facts from the officer either. Fault often turns on details nobody knows at the scene, such as the other driver's speed or phone use. Frost Law Group also advises people on calls from the other driver's insurance company, where the same caution applies.
Describe what you saw and did, answer the officer's questions truthfully, and leave conclusions to the evidence. Anything you say at the scene may come up later through the other driver, a witness or an adjuster. Your own policy likely requires you to report the crash to your insurer and cooperate, so do that as well. If anyone is hurt, Section 56-5-1260 also requires you to notify police right away. The statute names the agency by location, starting with town police inside a municipality.
What the Law Requires Before You Leave
Section 56-5-1230 lists the duties after a crash that injures someone or damages an attended vehicle. You must give your name, address and vehicle registration number, and show your license on request. You must also give reasonable help to anyone hurt. That includes arranging a trip to a doctor or hospital when treatment is plainly needed or requested.
Two hospitals with Summerville addresses run emergency rooms around the clock. They are HCA Healthcare Summerville Hospital at 295 Midland Parkway and Roper St. Francis Berkeley Hospital at 100 Callen Boulevard.
The paperwork continues after the scene clears. After most crashes an officer investigates, each driver or owner receives an insurance verification form, known as the FR-10. Section 56-9-350 gives you 15 days from the day the officer hands it over to return it to SCDMV. Skip it, and the statute lets the unreturned form stand as prima facie evidence, meaning proof that holds unless rebutted, that the car was uninsured.
Does Moving Your Car Out of Traffic Count Against You?
Not by itself. In a crash that damaged only vehicles, Section 56-5-1220(B) asks each driver to clear a drivable car that is blocking traffic. It also protects the driver who does so before police arrive.
Moving the car, standing alone, does not make that driver liable or at fault for the collision. The protection covers only the act of moving the car, not the driving that came before it. Take photos first if you safely can.
Ask a Summerville Car Accident Lawyer About Your Own Injuries
Tara L. Frost and Jack C. Frost can explain what happens if a car accident was your fault, or only partly your fault, under the policies that actually apply. They can also tell you whether your own injury claim looks worth pursuing under South Carolina's comparative fault rule.
Frost Law Group works from 128 Linwood Lane, Summerville, SC 29483. Bring the collision report number, your declarations page, any ticket you received and every letter from an insurer. Those papers show what the other side is claiming and what your coverage can answer.
Your free consultation stays confidential, and a caller reaches one of the two attorneys rather than a service. Dial (843) 419-6653, or if a call does not fit around your recovery, leave the attorneys a message online.
The attorneys at Frost Law Group
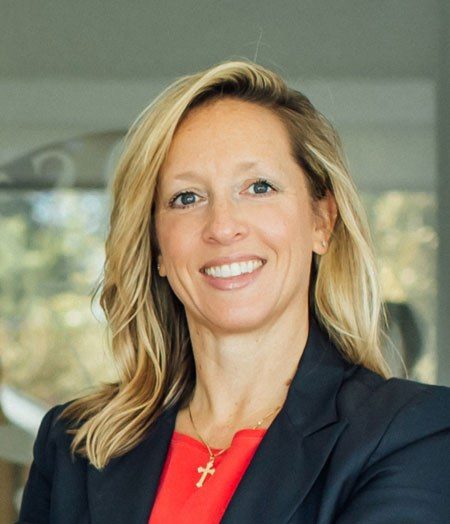 Tara L. FrostAttorney at Law · Personal injuryTara L. Frost focuses on personal injury, car accident and truck accident claims. A lifelong resident of the tri-county area, she meets clients at the Linwood Lane office in Summerville.
 Jack C. FrostAttorney at Law · Former Summerville police officer and Charleston County Sheriff's Office detectiveJack C. Frost spent fourteen years in law enforcement with the Summerville Police Department and the Charleston County Sheriff's Office before he practiced law.